
Quick Summary & Key Takeaways (Featured Snippet)
Fundamental Architectural Difference
The choice between a Systematic Investment Plan (SIP) and a Bank Fixed Deposit (FD) boils down to two distinct financial philosophies: Wealth Preservation versus Wealth Creation.
While Bank FDs protect the nominal rupee value of your capital, their post-tax returns frequently trail Consumer Price Index (CPI) inflation, eroding real purchasing power. Mutual fund SIPs harness rupee cost averaging and corporate profit expansion to create compounding wealth.
Recommended Video Tutorials & Practical Guides
Head-to-Head Comparison Matrix
| Evaluation Parameter | Bank Fixed Deposit (FD) | Equity Mutual Fund SIP |
|---|---|---|
| Expected Annual Returns | 6.50% - 7.50% p.a. (Fixed) | 12.00% - 15.00% CAGR (Market-linked) |
| Taxation Framework | Taxed at normal slab rates (up to 30% + cess) | 12.5% LTCG on gains above ₹1.25 Lakh exemption |
| Inflation Hedging | Negative to flat real return post-tax | Beats CPI inflation by 6% to 9% historically |
| Rupee Cost Averaging | No (Single lump-sum rate lock) | Yes (Buys more units when market drops) |
| Liquidity & Exit Penalty | 0.5% - 1% premature withdrawal penalty | Zero exit load after 12 months in most equity funds |
| Regulatory Guarantee | DICGC insurance up to ₹5,00,000 per bank | SEBI regulated; No guaranteed principal return |
Mathematical Wealth Compounding Simulation: ₹10,000 Monthly
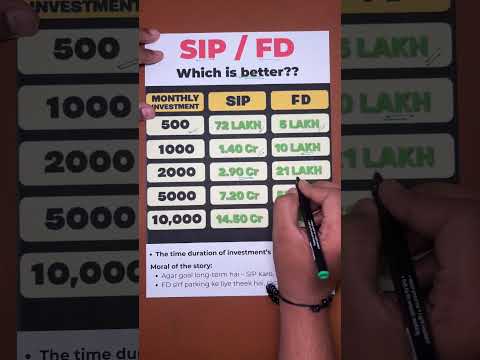
Assume an investor commits ₹10,000 every month over different time horizons. Let's compare an FD yielding 7.0% (taxed at 30% slab = net 4.9%) versus a diversified equity SIP generating 13.0% CAGR:
| Investment Horizon | Total Invested | Bank FD Value (Net Post-Tax) | Equity SIP Value (13% CAGR) | Wealth Difference |
|---|---|---|---|---|
| 5 Years | ₹6,00,000 | ₹6,80,450 | ₹8,42,100 | +₹1,61,650 |
| 10 Years | ₹12,00,000 | ₹15,48,200 | ₹24,65,800 | +₹9,17,600 |
| 15 Years | ₹18,00,000 | ₹26,54,300 | ₹55,50,200 | +₹28,95,900 |
| 20 Years | ₹24,00,000 | ₹40,65,100 | ₹1,14,55,000 | +₹73,89,900 |
Strategic Asset Allocation: When to Choose Which?
When Bank FDs Are Ideal
- Emergency reserve funds needed within 0 to 24 months.
- Senior citizens requiring guaranteed monthly interest cash flows.
- Fixed capital commitments (e.g., child's college admission fee due in 6 months).
- Conservative investors with zero appetite for short-term NAV drawdown.
When Mutual Fund SIPs Are Ideal
- Long-term life goals with a horizon of 5, 10, or 20+ years.
- Retirement accumulation and early financial independence (FIRE).
- Beating retail inflation and generating real purchasing power growth.
- Young salaried earners beginning their compounding journey.
Frequently Asked Questions
Can I pause or stop an ongoing SIP without penalty?
Yes. Unlike bank recurring deposits which levy penalty fees on premature termination, mutual fund SIPs can be paused, modified, or stopped at any time through your investment app with zero penal charges.
What is the tax rate on Mutual Fund gains if redeemed within 1 year?
If equity mutual fund units are redeemed within 12 months of purchase, the profit is categorized as Short-Term Capital Gains (STCG) and taxed at a flat rate of 20% (plus applicable surcharge and health/education cess).